Pre-retirement savings rates for renters – with and without investment cost improvements
Improving on Fran and Fred’s lifetime financial plan through lower investment costs
Fran and Fred Frugal, both age 30, are a married working couple with $100,000 in combined annual earned income. They want to understand how valuable different personal finance strategies could be to their lifetime finances and their retirement security. In a baseline projection scenario, they planned always to rent, not to have children, to retire at age 65, not to use any tax-deferred investments, and to pay average investment costs.
Obviously, in this baseline scenario Fran and Fran have NOT adopted many of the lifetime financial planning practices that would make it easier to achieve financial success in life. See the “Fran and Fred’s Baseline Lifetime Planning Assumptions:” section at the bottom of this article for more information about Fran and Fred’s current personal finances and their other lifetime financial planning assumptions.
In a series of articles, The Skilled Investor will compare different lifetime financial planning projections for Fran and Fred to illustrate the relative value of adopting different financial planning strategies. To find a list of other articles about Fran and Fred as renters, click “Age 30 Renters” in the right hand column under “Find More Articles on These Topics.”
How much should Fran and Fred save to have enough financial assets until age 95, when they adopt a very low lifetime investment costs strategy?
At age 30, Fran and Fred have begun to reevaluate their financial practices. They want to know how much they “need to save” or “could spend” this year and in the years ahead and still have enough over their lives until age 95.
In an investment cost improvement scenario over their baseline financial planning case, Fran and Fred decided to commit to a significant reduction in their lifetime investment costs. Instead of paying average investment costs during their lifetimes, they decided to pay much lower investment costs. They intend to pay investment costs that would be typical of a passive, broad market, index investment strategy that is also managed to have very low costs.
A customer comment from the sidebar: "VeriPlan is a big help. I'm in my mid 50's and have been a diligent saver and passable investor for many years. I am going through a work transition from salaried corporate employee to independent consultant, and my aging parents are needing financial help. Financial planning is particularly important to me and my family now. Thanks for making your product available. I've recommended it to a number of folks and will continue to do so." J.H. in Portland, OR
Find Home Financial Planning Software
A customer comment from the sidebar: "VeriPlan has been a very flexible home financial planning tool. It took me a few hours on a weekend to understand what VeriPlan could do and to enter our financial data. Our family financial affairs were scattered all over, and we lacked a comprehensive picture of what the future might hold for us. I wanted a clear understanding of our projected lifetime and retirement income, expenses, taxes, debts, real estate, financial assets, college investments, retirement investments, and everything else all together." S. L. in Altadena, CA
Discover Family Financial Planning Software
A customer comment from the sidebar: "You have done a great job of including the necessary instructions in VeriPlan, located close to where the modeling is happening. The thing I like about the VeriPlan User Guide is that it adds substantial additional commentary that I personally find very valuable. I was hunting for a capable and reasonably priced financial planning package, and VeriPlan is an awesome tool. The more I play around with it, the more valuable I find it. Your free user guide was what made me decide to get VeriPlan." C. A. in North Royalton, OH
Financial Planning Software for Individuals
A customer comment from the sidebar: "One of the stories that VeriPlan tells me is how much of my money could be lost to excessive investment costs. I just switched to some lower cost funds in my 401k. I loved updating VeriPlan with the new cost values just to see the red bar on the Total Assets chart get significantly thinner - quite a shocking difference." M. W. in Tulsa, OK
The Best DIY Retirement Planning Software
A customer comment from the sidebar: "I am extremely impressed with the depth of information that VeriPlan asks for and provides. VeriPlan seems much more detailed than one would expect for the very reasonable price. Although I am not a financial professional, I consider myself more financially educated than the most people of my age (62). I find that VeriPlan's depth to be just what we need for our retirement planning. I am glad I purchased it. Thanks." J. W. in Gainsville, FL
Financial Planning Software for Consumers
A customer comment from the sidebar: "I have been very happy with this software. I will put VeriPlan to work to help optimize our IRA to Roth conversions, while avoiding the IRMAA penalties if we can. We are in an opportunistic window for the next several years. I have been appalled by the lack of professional knowledge available with respect to the tax burden that will fall upon us when RMDs take effect. Most of the information I have found suggests that it isn't a problem. Luckily, this software will be of great benefit to chart our course." J. S. in Louisville, KY
Family Financial Planning Software
A customer comment from the sidebar: "I am a recently retired engineer, and I created a cash flow Excel spreadsheet for 25 years of retirement. So, I fully appreciate the data and potential variances that must be accounted for. Yet, mine is so very simple compared to VeriPlan. I love VeriPlan's concept of total control over inputs and parameters. Veriplan's objectives are very much like mine, but it has many, many more input and control options, and the price is spot on." L. G. in Southbridge, VA
Family Financial Planning Software for Consumers
A customer comment from the sidebar: "I've been using VeriPlan for a few weeks now, and it is everything I was looking for plus a whole lot more of what I didn't even know I needed. By simply switching VeriPlan to a state that does not have a state income tax, I can see how much I could save on traditional IRA distributions in retirement by moving to a state without income taxes. It is a real education in personal finance, and I think just about everyone would benefit from using this tool." T. H. in Silicon Valley CA
Financial Planning and Retirement Software for Home Use
Fran and Fred realize that reducing investment costs will take a some effort on their part. Instead of waiting to have costly brokers or advisors sell them expensive investments, they will seek out lower cost investments by themselves. Despite the additional effort on their part, their investment cost improvement scenario showed them that keeping their investment costs down could be worth far more than a million dollars over their lifetimes. Fran and Fred now understand that even average investment costs are simply outrageous and that their lifetime investment costs could make the difference between the success and failure of their lifetime financial plan.
For more information on investment costs, see these 15 articles in the “Controlling Investment Costs” section of The Skilled Investor’s main website. For more information on lower cost investments, see these 18 articles in the “Selecting Investment Funds” section of The Skilled Investor’s main website.
In the graphic below, Fran and Fred have generated a revised lifetime financial planning scenario, which assumes that they will: a) pay low investment costs over their lifetimes, and b) save at rates that might allow their financial assets to last just until they are 95. This graphic shows their projected annual pre-retirement savings rates for this scenario.
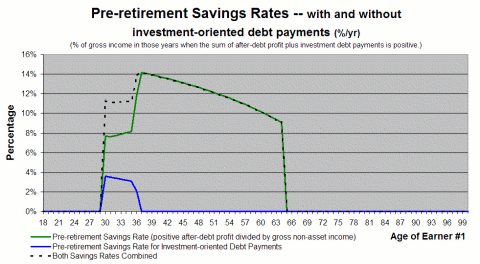
Note that their savings rates are lower in the first six years of their projection due to required debt payments. Also, their annual savings rates decline over the years due to increasing taxes related to their growing taxable assets. For an explanation of either of these situations, see this article about required savings in Fran and Fred’s baseline financial plan:
Retirement savings needs of renters — prior to any financial planning improvements.
A customer comment from the sidebar: "VeriPlan's financial projection graphics simply lay out what the future might hold for my family. Also, VeriPlan is a very fast and automated financial investment calculator that allows me to change anything and to test alternate investment decisions rapidly. Its integrated documentation explains clearly how it works, and it also includes a wealth of well-researched personal finance and investment information that has been very helpful." T. F. in Muncie, IN
Find Home Financial Planning Software
A customer comment from the sidebar: "I do most of my own financial modeling, and I like the way VeriPlan generates “what if” scenarios that I like to compare, such as possibly buying a rental property, selling my house and renting, moving social security retirement age payment timing, and pulling out IRA money after taxes. Plus, I like VeriPlan for its automated projection of detailed investment costs. Thanks for making a great product." K. W. in Naperville, IL
Discover Family Financial Planning Software
A customer comment from the sidebar: "I am 10 years out from retirement, and I needed to start thinking more seriously about having enough to retire on. I'm following the suggestions of you and others in opting for more hands-on retirement planning. I am also using lower cost index investing. There are too many wealth management companies out there, all ready to charge an arm and leg for what should be straightforward financial planning work." G. B. in Smith Mountain Lake, VA
Financial Planning Software for Individuals
A customer comment from the sidebar: "Larry, Hello again! I've continued to work with VeriPlan, and the more I work with it the more I'm amazed at how much it does. It's an incredible decision support tool for my financial planning. Since I have already built a model of my lifetime finances, it is easy to test new ideas as they come to me. Thanks again." M. W. R. in Austin, TX
Family Financial Planning Software
A customer comment from the sidebar: "I first learned about the zero federal taxes on long term capital gains when under the 25% marginal income tax rate from working with VeriPlan a number of years ago. I’m no longer working but not yet receiving RMD’s or social security so my ordinary income is relatively low. So I’ve been taking full advantage of zero federal capital gains taxes by selling off my high expense ratio mutual funds which have a lot of capital gains built in since I’ve held them a long time and then I reinvest them in index mutual funds which don’t generate as much capital gains distributions. So the education that you and VeriPlan provide has saved me thousands in taxes, not to mention the expenses on high cost mutual funds. Thanks again." M. D. in El Paso, TX
Family Financial Planning Software for Consumers
How do these annual savings rates compare to Fran and Fred’s baseline plan with average investment costs?
When Fran and Fred had projected to pay “average” investment costs in their baseline lifetime financial plan, their required annual pre-retirement savings rates were much higher. The following graphic shows these higher required savings rates.
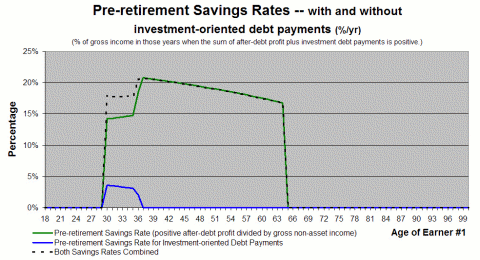
The two savings rate charts above have the same characteristic shapes due to required debt repayments in the first six years and increasing asset taxes on their exclusively taxable asset accounts thereafter. However, in each projection year there is roughly a 6 percentage point difference in the required savings rate between the “average” investment cost scenario and the low investment cost scenario. In effect, by reducing their investment costs they greatly reduce their savings requirements. Even so, they could end up at the same goal, which is to have adequate financial assets through age 95.
Conclusion: Reducing investment costs can dramatically lower required savings rates.
If they adopt the savings pattern in the second graphic above (the average investment cost scenario), Fran and Fred would have $53,050 in “real” constant purchasing power dollars to spend every year during their lives. However, if they adopt the savings pattern in the first graphic above while choosing investments with much lower costs, they would have about $59,630 to spend each year.
A customer comment from the sidebar: "I am a recently retired engineer, and I created a cash flow Excel spreadsheet for 25 years of retirement. So, I fully appreciate the data and potential variances that must be accounted for. Yet, mine is so very simple compared to VeriPlan. I love VeriPlan's concept of total control over inputs and parameters. Veriplan's objectives are very much like mine, but it has many, many more input and control options, and the price is spot on." L. G. in Southbridge, VA
Find Home Financial Planning Software
A customer comment from the sidebar: "Thanks for developing a great product. I have looked at Money Tree, Money Guide Pro, and some other FP software, and I have used Right Capital (a good product also, but still $100 per month). Yours is just as robust for a much more affordable price. I also extensively use Quicken for my finances, but the planning tool in it is kind of basic, so VeriPlan will complement Quicken very well." E. Z. in San Mateo, CA
Discover Family Financial Planning Software
A customer comment from the sidebar: "I spent parts of the past several days entering data into the VeriPlan workbook while digesting as much of the methodology as possible. My takeaway is that VeriPlan is an extraordinary tool, especially in its ability to generate projections based on detailed alternate scenarios. During the learning process, I also found it to be a wonderful financial education in its own right." S. N. in Sammamish, WA
Financial Planning Software for Individuals
A customer comment from the sidebar: "Previously I used some consumer retirement planners like New Retirement. What they offer is a projection of your financial situation that is wildly generalized. A generalized projection is probably better than having no projection at all and could very well be used for rough, long-term planning. However, for fine grained planning, such a system is wholly inadequate. VeriPlan is vastly superior in comprehensiveness and flexibility." T. D. in Edison, NJ
Family Financial Planning Software
A customer comment from the sidebar: "I purchased VeriPlan for the Roth conversion features. I enjoy VeriPlan and appreciate the thoroughness of the design and excellent commentary. I now work for (financial company name redacted) since retiring from (computer company name redacted) in a Retirement and Workplace Planning role. The accuracy, conciseness, and utility of the information presented by VeriPlan is great." M. S. in White Plains, NY
Family Financial Planning Software for Home Use
A customer comment from the sidebar: "I've been using VeriPlan for a few weeks now, and it is everything I was looking for plus a whole lot more of what I didn't even know I needed. By simply switching VeriPlan to a state that does not have a state income tax, I can see how much I could save on traditional IRA distributions in retirement by moving to a state without income taxes. It is a real education in personal finance, and I think just about everyone would benefit from using this tool. I am going to tell everyone I know about VeriPlan. Thank you very much for creating it. Your web sites are great, too." T. H. in Silicon Valley CA
Financial Planning and Retirement Software for Home Use
A customer comment from the sidebar: "I thought I would let you know that VeriPlan was the primary decision support tool in my decision to retire early, which was about 4 years ago now. And it has worked out really well. Since then I got married, and we have traveled to 10 countries -- some on mission trips. I had used the lifetime planners in Microsoft Money and Quicken but they were not robust enough to make a major decision with. In retrospect they are toys compared to VeriPlan. So VeriPlan has been a very big help to me. Also, I recently read your Lowest Cost Mutual Funds book, which was great. It brought a few things to my attention that I need to work on." Email update from T. H. in Silicon Valley
Family Financial Planning and Retirement Software
This means that Fran and Fred would have almost $6,600 more to spend every year out of their total gross income of $100,000! What they do not waste on unproductive investment costs flows back to them in terms of higher returns on their investment assets. Higher net returns reduce their savings requirements dramatically. In effect, it is much easier for Fran and Fred to find their own low cost investments while adopting a passive, broad market index investment strategy.
While it might seem easier to follow the recommendations of brokers and investment advisors, unfortunately their advice tends to be very expensive. Brokers and investment advisers may seem to make investing easier, but their direct costs and their tendency to lead you into excessively expensive investments tend to reduce your long-term net investment returns very significantly. As a result, you have to save far more over your working lifetime to make up the difference.
(For more on the subject of excessive advisory costs, see this article: “Pay Less to Get More” )
Subsequent articles in this series will illustrate the value to Fran and Fred of making long-term financial planning strategy improvements — taken one at a time or collectively.
In the next article, we will project what would happen, if Fran and Fred were to adopt low investment costs and keep their baseline savings rate high. Instead, they will determine how much earlier than age 65 that they might be able to retire, while still planning for their assets to last until age 95.
DO YOUR OWN LIFETIME FINANCIAL PLANNING — easily in your own home!
VeriPlan lets you focus on your own particular financial needs, circumstances, and goals. VeriPlan is the most powerful and sophisticated do-it-yourself financial planning software available to you.
As a fully integrated lifetime personal financial planner, VeriPlan automatically and instantly projects annual values over your lifetime for your family’s income, living expenses, debts, taxes, taxable and tax-deferred assets, and property. Every VeriPlan lifetime projection presents your personalized financial information net of your federal, state, and local taxes and your investment costs.
VeriPlan Is Simply The
Best Financial Planning Software
You Can Buy!
Only $57 for a license for ALL your household PCs
… with Free Shipping of the CD within the USA
Full 30-Day, 100% Money Back Guarantee — No Questions Asked
No Support Contract Required
No Need To Buy Upgrades, Since All Parameters Are User-Changeable
VeriPlan is a Great Product, a Great Deal,
and a Great Help with Your Personal Financial Planning.
Thank You Very Much for Your Order!
Note: We mail your VeriPlan CD on the next business day after PayPal has notified us of your order. When your order ships, we will send a shipment notification email to you using the email address supplied by PayPal. VeriPlan is shipped via the USPS, and deliveries typically take 3 to 10 days to arrive.
.
Fran and Fred’s Baseline Lifetime Planning Assumptions:
Fran and Fred Frugal, now age 30, are a married working couple with $100,000 in total annual earned income. Their major lifetime financial planning goals are to have enough financial assets until at least age 95, in case both live that long. These are Fran and Fred’s major baseline projection assumptions.
NOTE: Of course, some of Fran and Fred’s assumptions are not optimal. In various scenarios, we will change these assumptions to illustrate the relative value of improvements.
Fran and Fred expect the following:
WORKING INCOME: Both intend to work full-time, until retirement at age 65. They expect their earned income to grow with the rate of inflation.
RETIREMENT INCOME: They expect to collect 60% of currently quoted Social Security retirement benefits. They do not expect to have any pensions.
LIVING EXPENSES: They expect that their living expenses, before and after retirement, will grow with the rate of inflation. They plan always to rent and never to buy their residence. They do not plan to have any children. They expect that their retirement living expenses with be the same as their living expenses, when they were working.
DEBTS: They plan to pay off their current $20,000 in educational debts and $15,000 in credit card debt, as required by these debt contracts. Then, they plan to remain debt free throughout their lives.
TAXES: They plan to file income taxes using standard tax deductions. They expect always to live in Massachusetts, a state with a 5.3% flat income tax rate.
INVESTMENT STRATEGY: They now have $10,000 in money market funds, $10,000 in bond funds, and $10,000 in stock funds. They expect to use an average investment strategy with an average asset allocation throughout their lives. (IN THIS SCENARIO, THEY COMPARE LOW COST AND AVERAGE COST INVESTMENT STRATEGIES.) They intend to hold only money market fund, bond fund, and stock fund investments. They hope to earn very long-term historical asset class investment rates of return. They plan to pay average investment costs. They intend to buy-and-hold very broad market index funds, to withdraw assets only to meet expenses, and to pay long-term capital gains tax rates, as much as possible.
TAXABLE versus TAX-DEFERRED ACCOUNTS: They expect to use only taxable investment vehicles and do not plan to use any tax-advantaged retirement accounts.
TELL US THE PROJECTION YOU WOULD LIKE TO SEE FOR FRAN & FRED.
.
Related Personal and Retirement Financial Planning Articles